Personal Loans in North Dakota: What Licensed Lenders May Charge
North Dakota licenses non-bank consumer lenders as money brokers and caps their finance charges at 36% a year, origination charges included. Here is what the cap covers, who needs a license, and where to complain.
Cap 36% or less, by LendCedar Editorial Team Updated 6 minute read
In short
In North Dakota, a company that arranges or provides consumer loans to North Dakota residents needs a money broker license from the Department of Financial Institutions under NDCC chapter 13-04.1. A licensee may not charge finance charges above an annual rate of 36%, counting charges made at origination (NDCC 13-04.1-09.3). The statute sets no dollar ceiling on that cap, and on the National Consumer Law Center's comparison it allows about 36% APR on both a $2,000 two-year loan and a $10,000 five-year loan. Banks and credit unions are exempt.
- $2,000 loan cap
- 36% APR
- $10,000 loan cap
- 36% APR
- Late fee limit
- 5%, at most $20
- Licensed by
- ND DFI
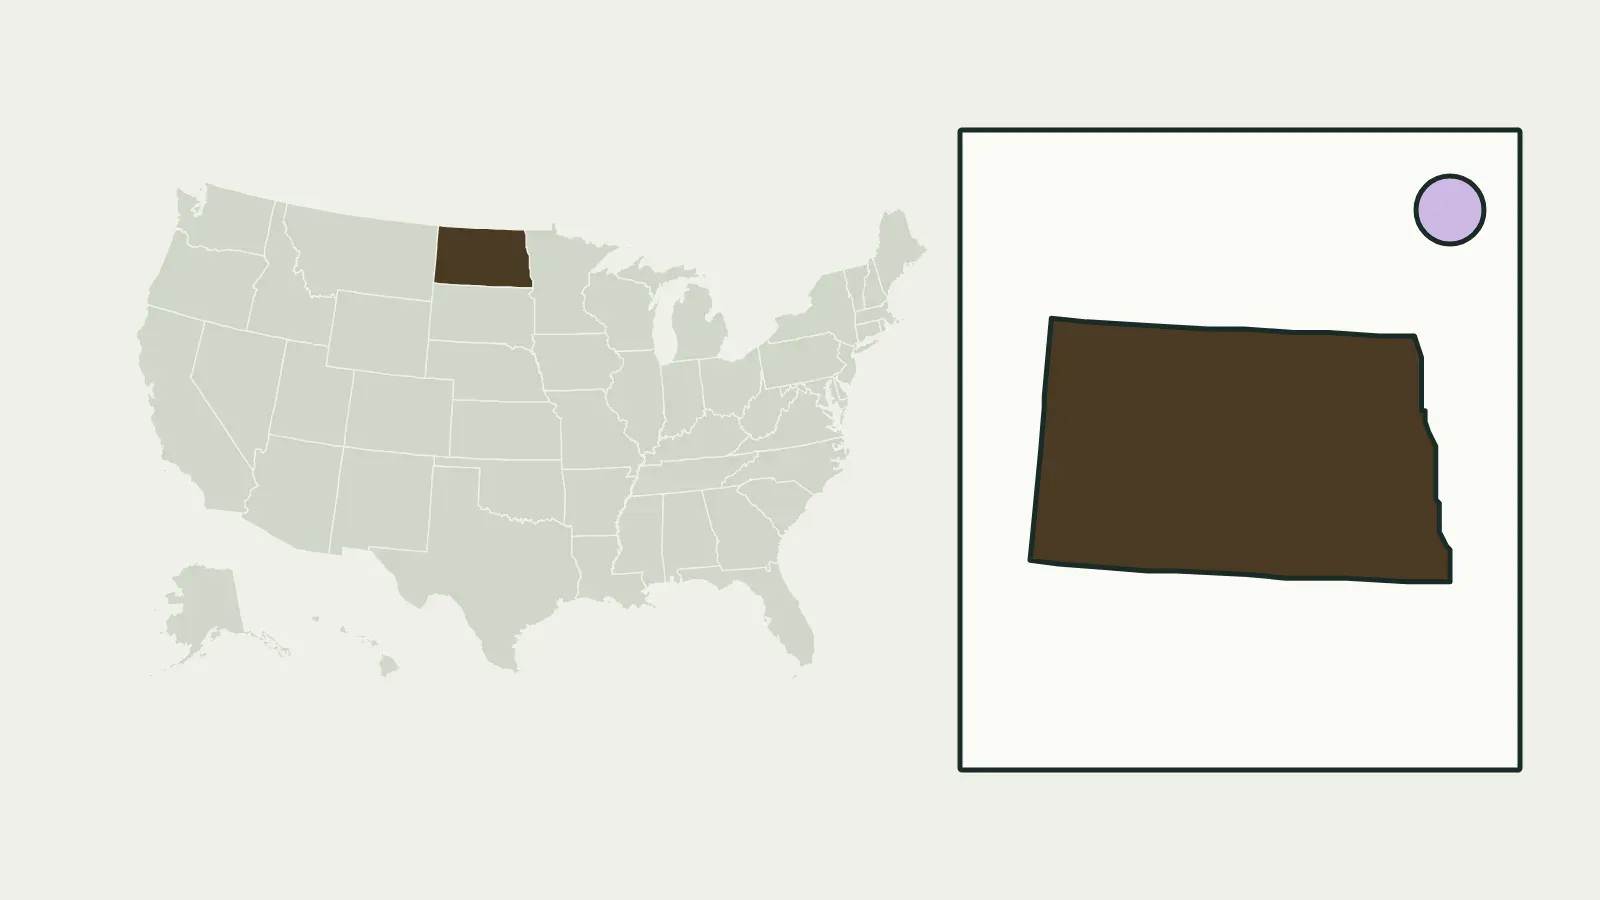
North Dakota at a glance
How the North Dakota cap works
The Money Brokers Act, NDCC chapter 13-04.1, defines money brokering as arranging or providing loans or leases as a form of financing, and applies when the borrower resides in North Dakota. Section 13-04.1-09.3 sets one flat limit for licensees: no finance charges above an annual rate of 36%, including charges incurred when the loan is made. The limit has no dollar threshold, so it reaches small and large loans alike.
| Charge or term | Limit |
|---|---|
| Finance charges, origination charges included | 36% a year |
| Late charge | 5% of the payment; $20 at most on loans of $50,000 or less |
| Refinance fees plus original-loan fees | $100 per calendar year |
| Extension or deferment charges | $100 per calendar year |
| Loans under $2,000 | 36 months at most, no balloon payment |
Because origination charges count toward the 36%, a lender cannot keep the rate at the limit and add a large upfront fee on top. Look at the APR, not only the interest rate, and check the amount financed: a fee taken from the loan means you receive less than you borrow. The net proceeds calculator shows how much reaches you.
How North Dakota compares with its neighbors
On the National Consumer Law Center's comparison of a $2,000 two-year loan, North Dakota matches South Dakota and Montana at about 36%, while Minnesota allows about 33%. On a $10,000 five-year loan the gap is wider: North Dakota allows about 36%, Minnesota about 22%. The rules that apply follow the lender's license and your state of residence. The state rules map shows every state side by side.
Who needs a license and who does not
No one may engage in money brokering in North Dakota without a money broker license (NDCC 13-04.1-02). The test is where the borrower lives, so a lender based elsewhere that lends to North Dakota residents is covered. Helping an unlicensed business operate is itself prohibited, and violations are a class C felony, with civil penalties of up to $100,000 per occurrence.
- Banks, credit unions, savings and loan associations, trust companies and insurance companies are exempt (NDCC 13-04.1-02.1), and a bank may charge the rates its home state allows.
- Online lenders that partner with a bank may make loans through that bank, which can put the loan outside the 36% cap. Ask who the lender of record is.
- Payday lenders are licensed separately as deferred presentment service providers. Our sister site Lendmira covers them on its North Dakota lending laws page.
Fees and practices the law forbids
- No precomputed loans: a licensee may not make an agreement that is a precomputed loan, so interest runs on the actual balance and paying early saves interest.
- No advance fees from unlicensed brokers: only a licensee may take a fee before the loan is funded.
- No bait rates: a licensee may not advertise rates or terms that are not actually available, or use unfair or deceptive practices.
- Property insurance is limited to the replacement cost of the property, if the lender requires it.
A fee asked before funding is still a warning sign with any lender you have not checked. Our guide on how to verify a lender explains what to look up first.
Check a lender and file a complaint
- Confirm the license before you apply: ask the lender for its North Dakota money broker license and check it with the Department of Financial Institutions at 701-328-9933.
- Keep the loan papers: the Truth in Lending disclosure, the agreement and any messages about fees.
- File a complaint against a licensed or chartered company at https://www.nd.gov/dfi/file-complaint.
- Send a complaint to the CFPB as well if the lender is a bank or a bank partner, or if you are unsure who regulates it.
Sources
- NDCC chapter 13-04.1 — Money Brokers (North Dakota Legislative Branch)
- North Dakota Department of Financial Institutions — licensing and complaints
- State APR caps for $500, $2,000 and $10,000 installment loans, December 2025 (National Consumer Law Center)
We checked the facts on this page against these sources on October 27, 2026. The 36% limit and the fee limits are written into NDCC 13-04.1-09.3 itself.
Questions people ask
What is the maximum interest rate on a personal loan in North Dakota?
A licensed money broker may not charge finance charges above an annual rate of 36%, including charges made at origination, under NDCC 13-04.1-09.3. The cap has no dollar limit.
What late fee can a North Dakota lender charge?
A late charge may not exceed 5% of the payment, and on loans of $50,000 or less it may not exceed $20 per late payment. See late fees and returned payments.
Do the North Dakota caps apply to banks and credit unions?
No. Banks, credit unions and other chartered institutions are exempt from the Money Brokers Act, and a bank can charge the rate allowed in its home state.
Who regulates personal loan lenders in North Dakota?
The North Dakota Department of Financial Institutions licenses money brokers and takes complaints online or at 701-328-9933.
Ask lenders for real offers
Describe the loan you have in mind. LendCedar passes your request to lenders and loan brokers who may contact you with offers; you compare them and decide.
- The loan you have in mind: amount, purpose, credit and income.
- Your contact details and your consent to be contacted.
- A lender or loan broker may contact you with an offer. Nothing is decided until you sign with a lender.
LendCedar is not a lender or a loan broker and does not make credit decisions.
You pay LendCedar nothing. Lenders and loan brokers pay us for requests, and they set their own rates and terms. How we make money.
Nearby in the guide
-
Offer term
Late fees and returned payments
Where the late charge appears, why the APR leaves it out, state limits in Ohio and Florida, and federal rules.
-
Step
Verify a lender
Find the license on NMLS or with your state, match the lender of record and spot advance-fee scams.
-
Offer term
Prepayment penalties
Simple-interest vs. precomputed loans, the Rule of 78s, and the line that says if early payoff costs extra.