Personal Loans in Montana: What Licensed Lenders May Charge
Montana caps interest on loans from licensed consumer lenders at 36% a year, a limit voters wrote into law in 2010. Here is what the cap covers, who needs a license, and where to check a lender.
Cap 36% or less, by LendCedar Editorial Team Updated 5 minute read
In short
A company that makes consumer loans in Montana needs a consumer loan license under the Montana Consumer Loan Act, Title 32, chapter 5 of the Montana Code. Section 32-5-301 caps its interest at 36% a year, a limit set by Initiative Measure No. 164, approved by voters on November 2, 2010. Besides interest, the lender may charge only a few listed fees, such as a past-due fee of the greater of $15 or 5%, up to $50. The Division of Banking and Financial Institutions licenses lenders through NMLS.
- $2,000 loan cap
- 36% APR
- $10,000 loan cap
- 36% APR
- Late or deferral fee
- $15 or 5%, up to $50
- Licensed by
- Banking Division
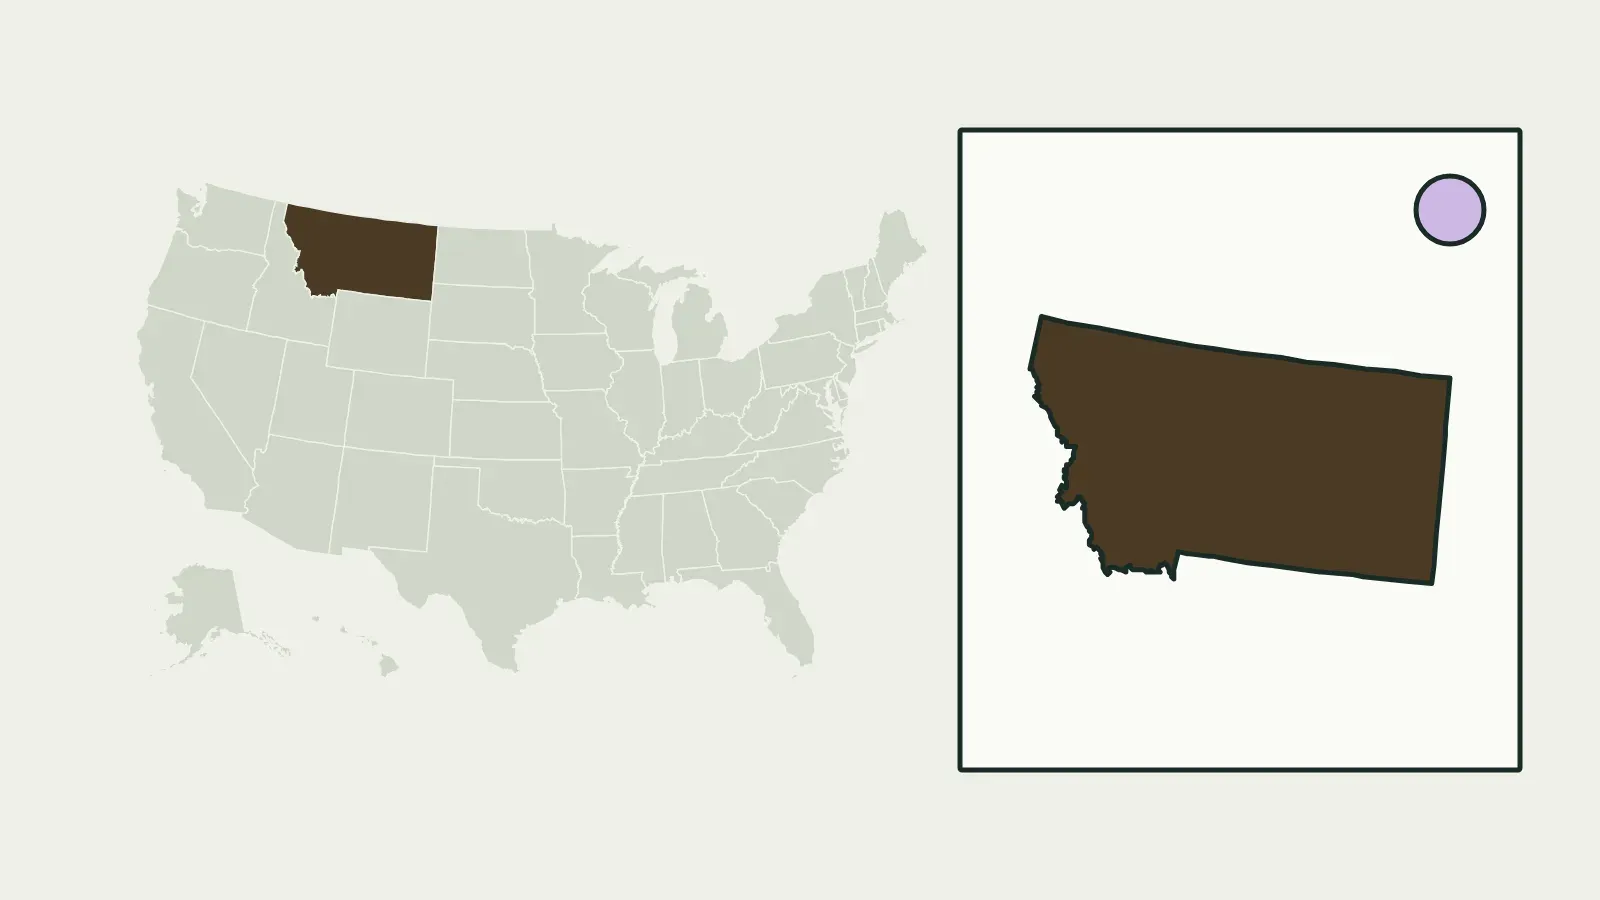
Montana at a glance
How the Montana 36% cap works
Section 32-5-301 is short and strict. A licensee may charge interest, but the interest may not exceed 36% a year. The fees for a deferral or a past-due payment are counted outside that 36%, and no other fees or charges may be contracted for or received except those the chapter authorizes. A licensee may not split one loan into several contracts to get around the limits.
| Charge | Limit |
|---|---|
| Interest | Up to 36% a year |
| Deferral fee, each deferral | Greater of $15 or 5% of the amount due, up to $50 |
| Past-due fee, once per past-due amount | Greater of $15 or 5% of the amount past due, up to $50 |
| Third-party fees, at your option | Added to principal: filing, credit insurance, appraisal, credit report and similar fees |
If a licensee collects more than the law allows, it must forfeit to you double the excess amount. Because third-party costs and credit insurance can be added to the principal, compare the amount financed and the APR on your Truth in Lending disclosure, not only the rate.
At the cap, the cost adds up quickly on a longer loan. A $2,000 loan at 36% repaid in 24 monthly payments costs $118.09 a month, with $834.16 in interest. A $10,000 loan at 36% over 60 months costs $361.33 a month, and the interest, $11,679.80, is more than the amount borrowed. These are worked examples, not offers; the loan term calculator shows how a shorter term changes the total.
How Montana compares with its neighbors
On the National Consumer Law Center's comparison of a $2,000 two-year loan, North Dakota and South Dakota also sit at 36% and Wyoming at about 31%, while Idaho has no numeric cap beyond an unconscionability standard. Your state of residence and the lender's license decide which rules apply. The state rules map shows every state side by side.
Who needs a license and who does not
Section 32-5-103 bars anyone from making consumer loans, or collecting payments on them, except as the Consumer Loan Act allows. The rule reaches anyone who tries to avoid it by any device, subterfuge or pretense, and a loan made by an unlicensed lender that is not exempt is void: the lender may not collect or keep any principal, interest or fees. Companies that service loans made under the Act must also be licensed to collect them.
- Banks, savings associations, trust companies and credit unions are exempt from the chapter. An out-of-state bank may charge the rates its home state allows.
- Occasional private lenders who make fewer than four consumer loans a year with their own money are also exempt if they do not hold themselves out as licensees.
- Online lenders that partner with a bank may lend through the bank. Ask who the lender of record is.
- Payday and title loans are covered by our sister site Lendmira on its Montana lending laws page.
Check a lender and file a complaint
- Look up the license in NMLS Consumer Access; the Division of Banking and Financial Institutions does all of its licensing through NMLS.
- Contact the lender first by letter or phone, and keep the Truth in Lending disclosure, the agreement and any messages about fees.
- File a written complaint with the Division using its complaint form, sent by email, mail or fax. Oral complaints are not accepted.
- Send a complaint to the CFPB as well if the lender is a bank or a bank partner, or if you are unsure who regulates it.
A request for a fee before approval or funding is a warning sign. How to verify a lender lists the other checks, and if you are denied covers what to do next.
Sources
- Montana Code Annotated 32-5-301 — Interest and fees (Montana Legislature, 2025 code)
- Montana Code Annotated 32-5-103 — Engaging in business of making consumer loans restricted (Montana Legislature)
- Division of Banking and Financial Institutions — consumer loan licensing
- Division of Banking and Financial Institutions — file a complaint
- State APR caps for $500, $2,000 and $10,000 installment loans, December 2025 (National Consumer Law Center)
We checked the facts on this page against these sources on October 27, 2026. Section 32-5-301 was last amended in 2015; the 36% limit dates from the 2010 ballot measure.
Questions people ask
What is the maximum interest rate on a personal loan in Montana?
For a lender licensed under the Montana Consumer Loan Act, 36% a year under section 32-5-301. Deferral and past-due fees are allowed on top, each the greater of $15 or 5% of the amount, up to $50.
Where did the Montana 36% cap come from?
Voters approved Initiative Measure No. 164 on November 2, 2010, and it amended section 32-5-301 to set the 36% limit.
What happens if an unlicensed lender makes me a loan in Montana?
Under section 32-5-103, a consumer loan made by an unlicensed, non-exempt lender is void, and the lender may not collect or keep principal, interest or fees. Report it to the Division of Banking and Financial Institutions.
Do the Montana limits apply to banks and credit unions?
No. Banks, savings associations, trust companies and credit unions are exempt from the Consumer Loan Act, and a bank can charge the rate allowed in its home state.
Ask lenders for real offers
Describe the loan you have in mind. LendCedar passes your request to lenders and loan brokers who may contact you with offers; you compare them and decide.
- The loan you have in mind: amount, purpose, credit and income.
- Your contact details and your consent to be contacted.
- A lender or loan broker may contact you with an offer. Nothing is decided until you sign with a lender.
LendCedar is not a lender or a loan broker and does not make credit decisions.
You pay LendCedar nothing. Lenders and loan brokers pay us for requests, and they set their own rates and terms. How we make money.
Nearby in the guide
-
Offer term
Total cost of a loan
Finance charge, APR and total of payments, with three worked offers for the same $10,000 loan.
-
Step
Verify a lender
Find the license on NMLS or with your state, match the lender of record and spot advance-fee scams.
-
Offer term
Late fees and returned payments
Where the late charge appears, why the APR leaves it out, state limits in Ohio and Florida, and federal rules.