Personal Loans in Missouri: No Rate Cap, but Licensed Lenders
Missouri lets a licensed lender charge whatever interest rate you agree to on most personal loans. The law limits fees instead and requires a state license. Here is what that means and how to check a lender.
No numeric cap, by LendCedar Editorial Team Updated 6 minute read
In short
Missouri has no numeric interest rate cap on most consumer loans from licensed lenders: section 408.100 of the Revised Statutes lets the lender charge interest on the unpaid balance at rates agreed to by the parties. What the law limits is fees, such as an up-front fee of no more than 10% of the loan or $100, and late charges. Lenders making consumer credit or consumer installment loans must be licensed by the Missouri Division of Finance. Because there is no ceiling, the APR you are offered is the number to compare.
- $2,000 loan cap
- No cap
- $10,000 loan cap
- No cap
- Interest rate
- As agreed by the parties
- Licensed by
- Division of Finance
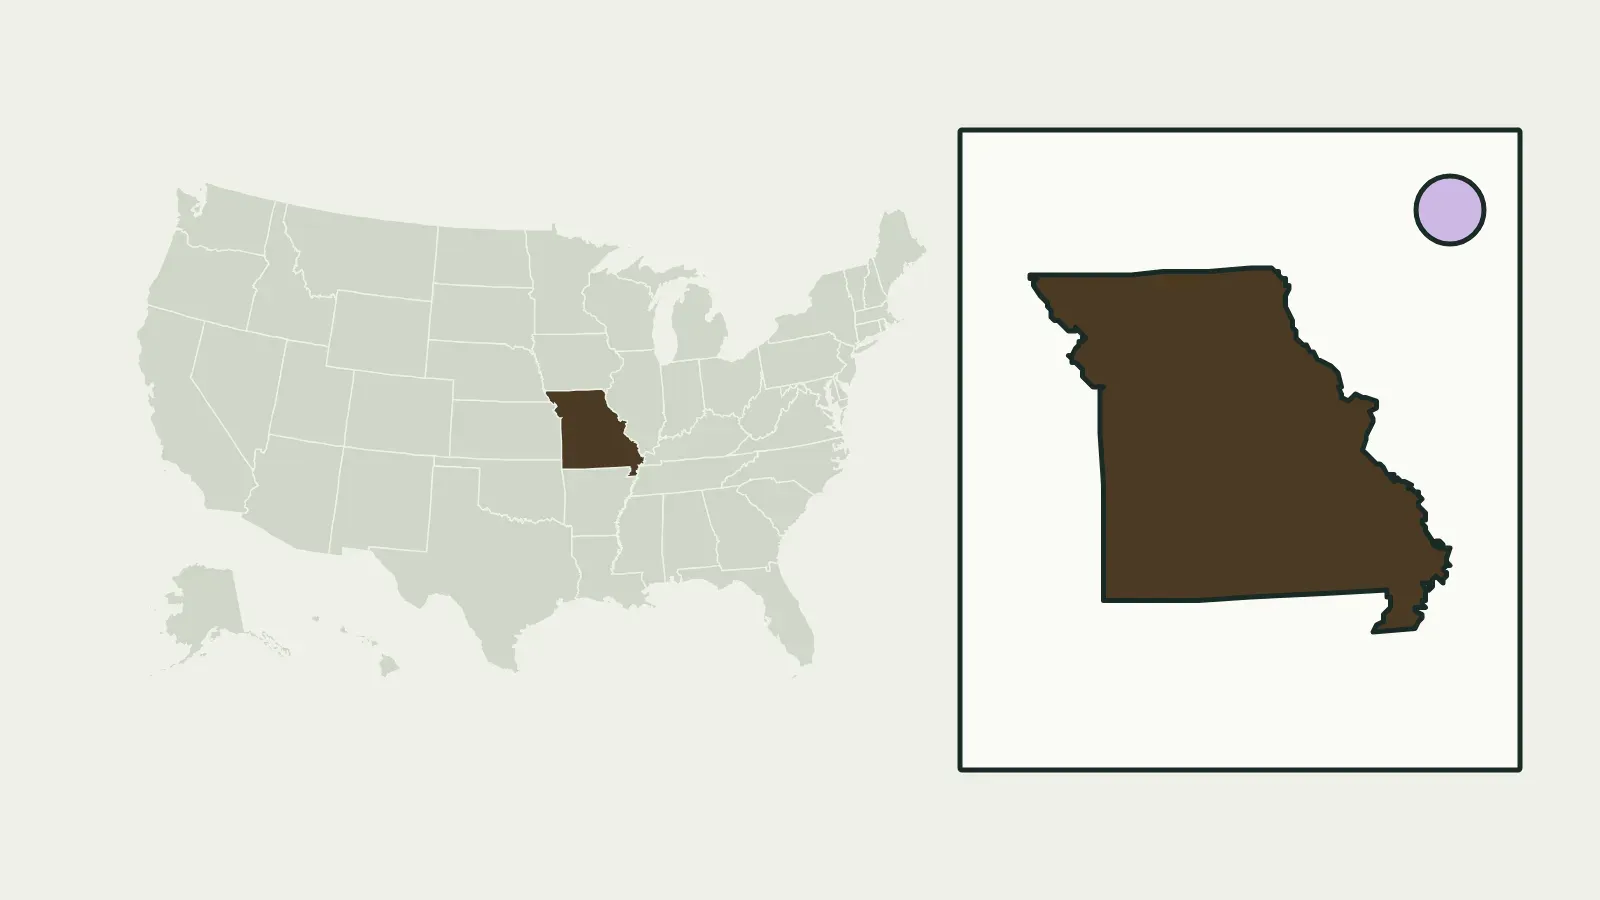
Missouri at a glance
How Missouri sets loan prices
Section 408.100 applies to loans that are not made under some other Missouri law, apart from loans secured by real estate. On those loans any person, firm or corporation may charge interest on the unpaid principal balance at rates agreed to by the parties. There is no percentage ceiling in the section, so the National Consumer Law Center, which compares state caps, lists Missouri as one of two states with no cap at all on a $2,000 or a $10,000 installment loan from a licensed lender.
A consumer installment loan under section 408.510 may be secured or unsecured and of any amount, but it must be repayable in at least four substantially equal installments over at least 120 days. Its lender charges interest and fees under sections 408.100, 408.140 and 408.170.
The spread can be wide. A $2,000 loan repaid in 24 monthly payments costs $118.09 a month and $834.16 in finance charges at 36% APR, but $193.93 a month and $2,654.32 in finance charges at 99% APR. These are worked examples, not offers.
The fees Missouri does limit
Section 408.140, last amended in 2024, lists the extra charges a lender may add to these loans. The main ones for a personal installment loan are below.
| Fee | Limit |
|---|---|
| Up-front fee, loans of 30 days or longer (not open-end) | 10% of the principal, up to $100; none on an extension, refinance or renewal |
| Late charge, installment at least 15 days past due | Greater of 5% of the installment or $15, up to $50 |
| Late charge, installment of $25 or less | Up to $5 |
| Returned check | A service fee set by another statute, plus the bank's actual fees |
Insurance premiums may also be charged, including credit life, health, accident or involuntary unemployment coverage, and the lender may charge the actual cost of a credit report. Read credit insurance and add-ons before you agree to any coverage.
Who needs a license and who does not
A business that makes consumer credit loans, meaning loans for personal, family or household purposes of $500 or more, is a supervised lender under sections 367.100 and following and must be licensed by the Division of Finance. A consumer installment lender is licensed in the same manner and on the same terms. A person who makes only occasional loans is not treated as a lender.
- Banks and credit unions answer to separate charters and regulators. An out-of-state bank may charge the rates its home state allows.
- Online lenders that partner with a bank may lend through that bank. Ask who the lender of record is, because that decides which rules apply.
- Payday and title loans follow their own Missouri rules. Our sister site Lendmira covers them on its Missouri lending laws page.
How Missouri compares with its neighbors
Every state bordering Missouri sets some limit. On the National Consumer Law Center's comparison of a $2,000 two-year loan, Arkansas caps the price at about 17% APR, Illinois and Iowa at 36%, Kansas at about 38% and Oklahoma at about 56%. If you live near a state line, your state of residence and the lender's license decide which rules apply. The state rules map shows every state.
Check a lender and file a complaint
- Look up the license with the Division of Finance's bank and licensee search before you apply.
- Keep the loan papers: the Truth in Lending disclosure, the agreement and any messages about fees.
- Complain to the Division of Finance through its consumer complaints page if a licensed lender charges fees the law does not allow.
- Send a complaint to the CFPB as well if the lender is a bank or a bank partner, or if you are unsure who regulates it.
A fee demanded before approval or funding is a warning sign. How to verify a lender lists the other checks.
Sources
- Missouri Revised Statutes section 408.100 — Applicability, rate of interest (Revisor of Statutes)
- Missouri Revised Statutes section 408.140 — Additional charges permitted (Revisor of Statutes)
- Missouri Revised Statutes section 408.510 — Consumer installment lenders (Revisor of Statutes)
- Missouri Revised Statutes section 367.100 — Consumer credit loan definitions (Revisor of Statutes)
- Missouri Division of Finance — consumer complaints and licensee search
- State APR caps for $500, $2,000 and $10,000 installment loans, December 2025 (National Consumer Law Center)
We checked the facts on this page against these sources on October 27, 2026. Section 408.140 was last amended by 2024 Senate Bill 1359, effective August 28, 2024.
Questions people ask
Is there a maximum interest rate on personal loans in Missouri?
Not a numeric one for most consumer loans from licensed lenders. Section 408.100 allows interest on the unpaid balance at rates agreed to by the parties.
What fees can a Missouri lender charge on a personal loan?
Section 408.140 allows an up-front fee of up to 10% of the principal, capped at $100, on loans of 30 days or longer, plus limited late charges, returned check fees, insurance premiums and the cost of a credit report.
What is a consumer installment loan in Missouri?
A secured or unsecured loan of any amount, repayable in at least four substantially equal installments over at least 120 days, made by a lender licensed by the Division of Finance.
How do I check a Missouri lender?
Search the Division of Finance licensee lookup, and file a complaint on its consumer complaints page if needed. See how to verify a lender.
Ask lenders for real offers
Describe the loan you have in mind. LendCedar passes your request to lenders and loan brokers who may contact you with offers; you compare them and decide.
- The loan you have in mind: amount, purpose, credit and income.
- Your contact details and your consent to be contacted.
- A lender or loan broker may contact you with an offer. Nothing is decided until you sign with a lender.
LendCedar is not a lender or a loan broker and does not make credit decisions.
You pay LendCedar nothing. Lenders and loan brokers pay us for requests, and they set their own rates and terms. How we make money.
Nearby in the guide
-
Offer term
Total cost of a loan
Finance charge, APR and total of payments, with three worked offers for the same $10,000 loan.
-
Step
Verify a lender
Find the license on NMLS or with your state, match the lender of record and spot advance-fee scams.
-
Offer term
Late fees and returned payments
Where the late charge appears, why the APR leaves it out, state limits in Ohio and Florida, and federal rules.