Personal Loans in Michigan: What Licensed Lenders May Charge
Michigan caps the interest on consumer loans from licensed lenders at a flat 25% a year, plus a limited processing fee. Here is how the cap works, who needs a license, and where to check a lender.
Cap 36% or less, by LendCedar Editorial Team Updated 6 minute read
In short
A Michigan finance company that makes personal loans needs a license under the Regulatory Loan Act from the Department of Insurance and Financial Services (DIFS), unless it holds a Consumer Financial Services Act license instead. Under the Credit Reform Act, these lenders may charge interest of up to 25% a year, plus a processing fee of up to 5% of the principal, capped at a dollar amount adjusted for inflation. All in, that allows about 30% APR on a $2,000 two-year loan and about 27% on a $10,000 five-year loan.
- $2,000 loan cap
- 30% APR
- $10,000 loan cap
- 27% APR
- Interest cap
- 25% a year
- Licensed by
- DIFS
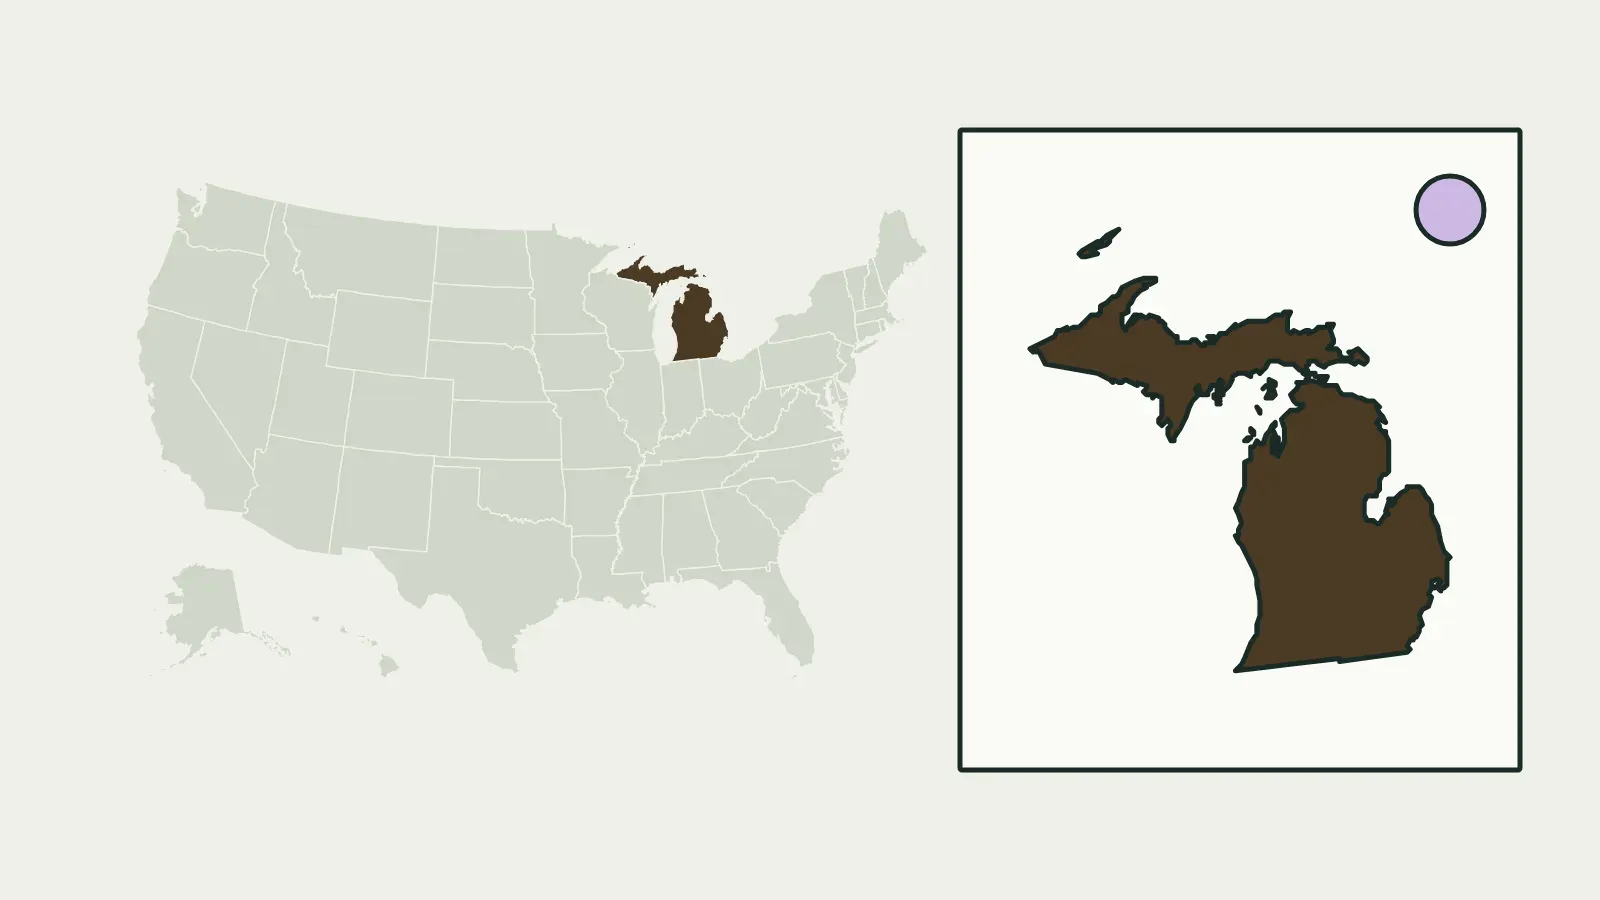
Michigan at a glance
How the Michigan rate cap works
Michigan splits the rule across two laws. The Regulatory Loan Act, MCL 493.1 and following, licenses the lender and says it may charge interest only up to the rate the Credit Reform Act allows. Section 445.1854 of the Credit Reform Act then sets that rate for a regulated lender at no more than 25% a year, and interest on a consumer loan must be figured on the unpaid balance.
| Charge | Limit | Where in the law |
|---|---|---|
| Interest | 25% a year | MCL 445.1854 |
| Loan processing fee, closed-end loan | 5% of principal, up to $250, adjusted every 2 years | MCL 493.13 |
| Late fee, after the grace period | $15 or 5% of the installment, whichever is greater | MCL 445.1856 |
| Dishonored check fee | $25 | MCL 445.1856 |
The $250 limit on the processing fee is the base amount in the statute; it is adjusted every two years for changes in consumer prices. Charges may not be collected in advance or compounded. Because the processing fee is part of the finance charge, the APR on your Truth in Lending disclosure will be higher than the 25% interest rate on a small loan.
How Michigan compares with its neighbors
On the National Consumer Law Center's comparison of a $2,000 two-year loan, Michigan's limit of about 30% is close to Ohio's 31% and well below Indiana's 40%. Wisconsin has no numeric cap. Your state of residence and the lender's license decide which rules apply. The state rules map shows every state side by side.
Who needs a license and who does not
The Regulatory Loan Act bars a person from the business of making loans without a license from the commissioner, unless the person is licensed under the Consumer Financial Services Act. A regulatory loan is a loan by a licensee to an individual for personal, family or household use.
- Banks and credit unions are depository institutions with their own charters and supervisors. An out-of-state bank may charge the rates its home state allows.
- Online lenders that partner with a bank may make loans through that bank, which can put the loan outside the 25% cap. Ask who the lender of record is.
- Payday and auto title loans are not covered here. Our sister site Lendmira explains them on its Michigan lending laws page.
Paying early, insurance and other borrower rights
A licensee must let you pay ahead in any amount on a loan. It may first apply the payment to charges that have built up to that date, and the rest goes to principal. Because interest runs only on the unpaid balance, paying early cuts the interest you owe.
Credit insurance is your choice. A licensee may not require you to buy insurance as a condition of the loan; if you choose it, the premium can be added to the principal. Read credit insurance and add-ons before you agree to any extra product.
Check a lender and file a complaint
- Look up the license in the DIFS Locator at difs.state.mi.us/locators, by the company's name, before you apply.
- Keep the loan papers: the Truth in Lending disclosure, the agreement and any messages about fees.
- Complain to DIFS through its online complaint page or by phone at 877-999-6442, Monday through Friday, 8 a.m. to 5 p.m.
- Send a complaint to the CFPB as well if the lender is a bank or a bank partner, or if you are unsure who regulates it.
A fee demanded before approval or funding is a warning sign. How to verify a lender lists the other checks.
Sources
- Regulatory Loan Act, MCL chapter 493 (Michigan Legislature, compiled through PA 14 of 2025)
- Credit Reform Act, Act 162 of 1995, MCL 445.1851 to 445.1864 (Michigan Legislature)
- Michigan Department of Insurance and Financial Services — complaints and DIFS Locator
- State APR caps for $500, $2,000 and $10,000 installment loans, December 2025 (National Consumer Law Center)
We checked the facts on this page against these sources on October 27, 2026. The processing-fee dollar cap is adjusted every two years; check the current amount with DIFS.
Questions people ask
What is the maximum interest rate on a personal loan in Michigan?
For a lender licensed under the Regulatory Loan Act, 25% a year under the Credit Reform Act, plus a processing fee of up to 5% of the principal, capped at a dollar amount that is adjusted every two years.
What late fee can a Michigan lender charge?
A licensed non-bank lender may charge a late fee after the agreed grace period of no more than $15 or 5% of the installment, whichever is greater.
Do the Michigan caps apply to banks?
Not in the same way. Banks and credit unions follow their own charters and federal law, and an out-of-state bank may charge the rates its home state allows.
How do I know if a Michigan lender is licensed?
Search the company in the DIFS Locator or call DIFS at 877-999-6442. See how to verify a lender.
Ask lenders for real offers
Describe the loan you have in mind. LendCedar passes your request to lenders and loan brokers who may contact you with offers; you compare them and decide.
- The loan you have in mind: amount, purpose, credit and income.
- Your contact details and your consent to be contacted.
- A lender or loan broker may contact you with an offer. Nothing is decided until you sign with a lender.
LendCedar is not a lender or a loan broker and does not make credit decisions.
You pay LendCedar nothing. Lenders and loan brokers pay us for requests, and they set their own rates and terms. How we make money.
Nearby in the guide
-
Offer term
Total cost of a loan
Finance charge, APR and total of payments, with three worked offers for the same $10,000 loan.
-
Step
Verify a lender
Find the license on NMLS or with your state, match the lender of record and spot advance-fee scams.
-
Offer term
Credit insurance and add-ons
Credit life, disability and job-loss coverage: when it is optional, what it adds, how to cancel it.