Personal Loans in Maine: What Licensed Lenders May Charge
Maine's Consumer Credit Code caps personal loans with three rate tiers and a flat 18% limit for larger loans. Here is how they work, who needs a supervised lender license, and where to check a lender.
Cap 36% or less, by LendCedar Editorial Team Updated 5 minute read
In short
Maine limits the finance charge on a closed-end consumer loan in Title 9-A, section 2-401: up to 30% a year on the part of the unpaid balance of $2,000 or less, 24% on the part from $2,000 to $4,000 and 18% on the part above $4,000. When the amount financed is more than $8,000, the finance charge may not exceed 18% a year on the whole loan. A company that makes supervised loans needs a license from the Bureau of Consumer Credit Protection. The National Consumer Law Center puts the ceiling at about 30% APR on a $2,000 two-year loan and about 18% on a $10,000 five-year loan.
- $2,000 loan cap
- 30% APR
- $10,000 loan cap
- 18% APR
- Rate tiers
- 30% / 24% / 18%
- Licensed by
- Consumer Credit Protection
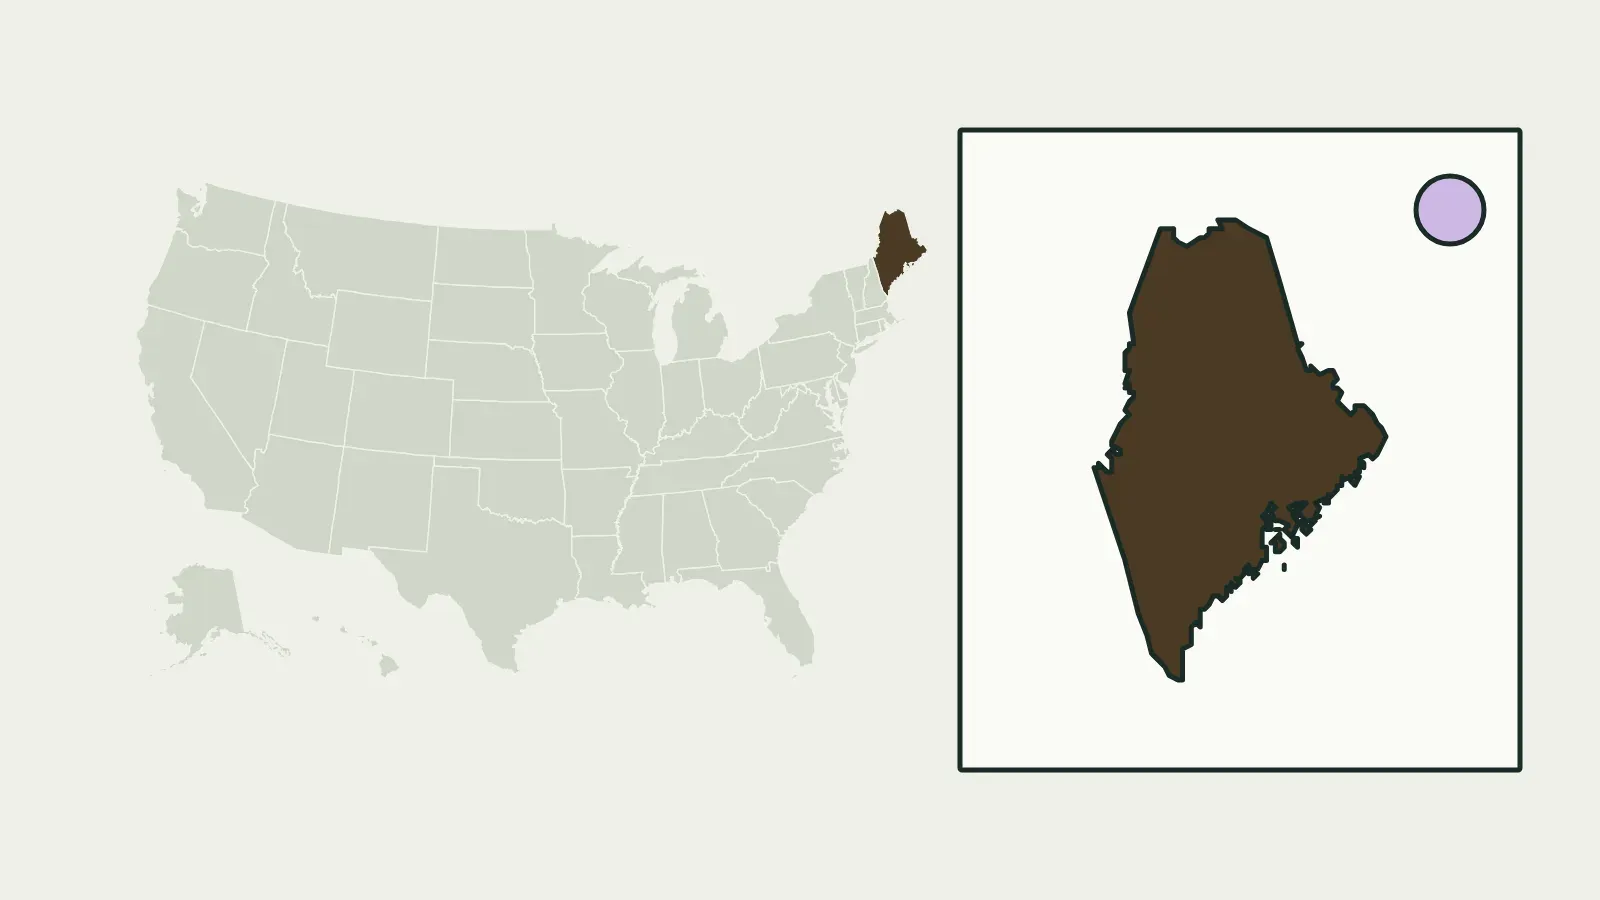
Maine at a glance
How the Maine rate tiers work
Section 2-401 of the Maine Consumer Credit Code applies each rate to its own part of the unpaid balance of the amount financed, so the blended rate falls as the loan grows. A second rule covers larger loans: when the amount financed is more than $8,000, the finance charge may not exceed 18% a year on the entire amount of the loan.
Here is how the two rules play out. On a $3,000 balance, the tiers allow 30% on $2,000 ($600 a year) and 24% on $1,000 ($240), or $840 a year, a blended 28%. On a $10,000 loan the tiers alone would allow about 21.6% at the start, but the 18% limit on the whole amount applies, so the most is $1,800 a year. These figures illustrate the limits; they are not offers.
| Part of the unpaid balance | Maximum yearly rate |
|---|---|
| $2,000 or less | 30% |
| $2,000.01 to $4,000 | 24% |
| Over $4,000 | 18% |
| Whole loan, if the amount financed is over $8,000 | 18% |
The section also sets a minimum charge the lender may collect even when the rates would produce less: $5 when the amount financed is $75 or less, $15 from $75 to $250, and $25 when it is $250 or more. Compare the APR on your Truth in Lending disclosure with these limits; it counts fees as well as interest.
How Maine compares with its neighbors
On the National Consumer Law Center's comparison of a $2,000 two-year loan, Vermont caps the loan at about 21% APR and Massachusetts at about 24%, while New Hampshire allows about 36%. For a $10,000 five-year loan, Maine's 18% matches Vermont and is below Massachusetts (20%) and New Hampshire (36%). The state rules map shows every state side by side.
Who needs a license and who does not
Under 9-A M.R.S. section 2-301, a person may not make supervised loans, take assignments of and collect on them, or service mortgage loans without first getting a license from the administrator. For non-bank lenders, that is the Bureau of Consumer Credit Protection in the Department of Professional and Financial Regulation. Applications go through NMLS.
- Supervised financial organizations and certain financial institution holding companies are exempt from the license requirement. Banks and credit unions answer to their own regulators, and a bank may charge the rates its home state allows.
- Online lenders that partner with a bank may make loans through that bank, which can put the loan under the bank's home-state rules rather than the Maine tiers. Ask who the lender of record is.
- Payday and title loans follow separate rules. Our sister site Lendmira covers them on its Maine lending laws page.
If a lender asks for a fee before it will approve or fund a loan, treat that as a warning sign; how to verify a lender explains what to check.
Check a lender and file a complaint
- Look up the license on NMLS Consumer Access before you apply. A non-bank lender making supervised loans to Mainers should show a Maine supervised lender license.
- Keep the loan papers: the Truth in Lending disclosure, the agreement and any messages about fees.
- Complain to the Bureau of Consumer Credit Protection online or with its mailed form, or call 800-332-8529 (toll-free in Maine) or 207-624-8527; TTY 888-577-6690.
- Send a complaint to the CFPB as well if the lender is a bank or a bank partner, or if you are unsure who regulates it.
Sources
- 9-A M.R.S. section 2-401, Finance charge for consumer loans (Maine Legislature)
- 9-A M.R.S. section 2-301, Authority to make supervised loans (Maine Legislature)
- File a complaint (Maine Bureau of Consumer Credit Protection)
- State APR caps for $500, $2,000 and $10,000 installment loans, December 2025 (National Consumer Law Center)
We checked the facts on this page against these sources on October 27, 2026. The rate tiers in section 2-401 were last amended in 1999; a 2025 revisor's correction did not change them.
Questions people ask
What is the maximum interest rate on a personal loan in Maine?
Under 9-A M.R.S. 2-401, up to 30% a year on the part of the unpaid balance of $2,000 or less, 24% on the part from $2,000 to $4,000 and 18% above $4,000. On a loan with an amount financed over $8,000, the limit is 18% a year on the whole amount.
Who licenses personal loan companies in Maine?
The Bureau of Consumer Credit Protection licenses supervised lenders under the Maine Consumer Credit Code. Banks and credit unions are exempt and supervised separately.
Can a Maine lender charge a minimum fee on a small loan?
Yes. Section 2-401 allows a minimum finance charge of $5, $15 or $25, depending on whether the amount financed is up to $75, from $75 to $250, or $250 or more.
How do I complain about a lender in Maine?
Contact the Bureau of Consumer Credit Protection online, by mail or at 800-332-8529 (in Maine). See how to verify a lender for checks to make first.
Ask lenders for real offers
Describe the loan you have in mind. LendCedar passes your request to lenders and loan brokers who may contact you with offers; you compare them and decide.
- The loan you have in mind: amount, purpose, credit and income.
- Your contact details and your consent to be contacted.
- A lender or loan broker may contact you with an offer. Nothing is decided until you sign with a lender.
LendCedar is not a lender or a loan broker and does not make credit decisions.
You pay LendCedar nothing. Lenders and loan brokers pay us for requests, and they set their own rates and terms. How we make money.
Nearby in the guide
-
Offer term
Total cost of a loan
Finance charge, APR and total of payments, with three worked offers for the same $10,000 loan.
-
Step
Verify a lender
Find the license on NMLS or with your state, match the lender of record and spot advance-fee scams.
-
Step
Where to borrow
Banks, credit unions, online lenders, CDFIs and finance companies: who regulates each and what they may charge.