Personal Loans in Delaware: No Rate Cap, but Rules Still Apply
Delaware lets a licensed lender charge whatever rate the loan agreement sets. The rules that protect you are about fees, prepayment, insurance and licensing. Here is what they say and where to check a lender.
No numeric cap, by LendCedar Editorial Team Updated 6 minute read
In short
A business that lends money in Delaware needs a license from the Office of the State Bank Commissioner under Title 5, Chapter 22 of the Delaware Code. That law sets no numeric rate cap: Section 2229 lets a licensee charge the rate the loan agreement provides. What it does limit is how a loan is run: one late charge per missed installment, capped at 5% of it; prepayment in full at any time with no prepayment fee; and credit insurance that may be offered but not required. Because the price is open, comparing the APR on each offer matters more here than in most states.
- $2,000 loan cap
- No cap
- $10,000 loan cap
- No cap
- Late fee limit
- 5% of the installment
- Licensed by
- State Bank Commissioner
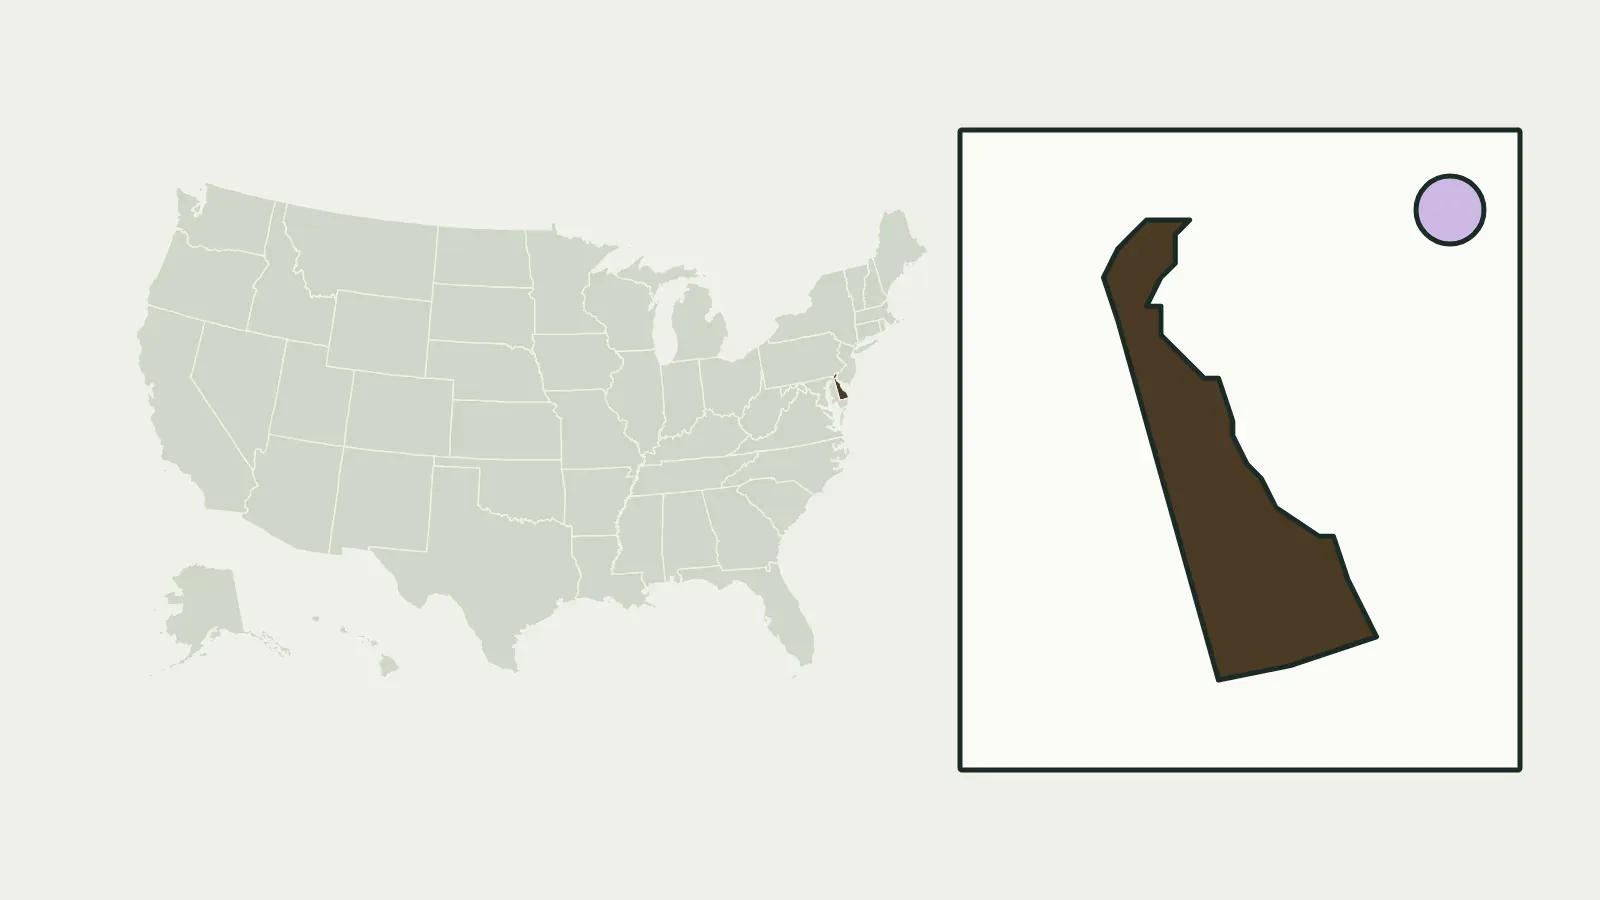
Delaware at a glance
Why Delaware has no rate cap
Closed-end installment loans from licensed lenders fall under Subchapter III of Chapter 22. Section 2229 lets a licensee charge interest at the rate or rates set by the agreement governing the loan, and Section 2237 says other Delaware laws that limit interest or charges do not apply to credit made under that subchapter. Section 2230 also allows a variable rate, including a rate that rises if you do not keep to the terms of the agreement.
The result is that the contract, not the statute, sets your price. The National Consumer Law Center, which compares state caps, lists Delaware as one of two states with no rate limit at all on a $2,000 two-year loan or a $10,000 five-year loan from a licensed lender. Most of the country caps those loans: the median cap among capping states is 34% APR on the $2,000 loan and 27% on the $10,000 loan.
How Delaware compares with its neighbors
| State | $2,000 two-year loan | $10,000 five-year loan |
|---|---|---|
| Delaware | No cap | No cap |
| Pennsylvania | About 24% APR | About 26% APR |
| Maryland | About 30% APR | About 25% APR |
| New Jersey | About 30% APR | About 30% APR |
The $2,000 figures are current as of September 2025 and the $10,000 figures as of August 2023. Which state's rules apply depends on the lender's license and where you live, not on where the lender is based. The state rules map shows every state.
Who needs a Delaware license
Section 2202 requires every person who wants to transact the business of lending money in Delaware to get a license. Someone who makes no more than five loans in any 12-month period is not treated as being in the lending business.
- Banks, federal credit unions and insurance companies are outside the chapter, as are lenders operating under another Delaware or federal law.
- Online lenders that partner with a bank may make loans through that bank. Ask who the lender of record is, since that decides which rules and which regulator apply.
- Short-term consumer loans of $1,000 or less with a repayment period under 60 days have extra rules in Section 2235A, including a limit of five such loans from all licensees in 12 months. Our sister site Lendmira covers payday and title loans on its Delaware page.
What the law still limits
Late charges
Section 2231 allows no more than one delinquency charge for any single installment, and it may not be more than 5% of the overdue installment. See late fees and returned payments.
Paying early
Section 2234 lets you prepay a loan in full at any time. A lender may not charge an individual borrower a prepayment fee, except on a residential mortgage, and precomputed interest must be refunded.
Credit insurance
Section 2233 lets a licensee ask, but not require, you to buy credit insurance. If you prepay, unearned premiums are refunded.
Other fees
Section 2231 allows reasonable fees for services rendered or expenses incurred in good faith, within a schedule set by the Commissioner. Ask for every fee in writing before you sign.
Check a lender and file a complaint
- Find the license. The State Bank Commissioner publishes lists of licensed non-depository institutions on banking.delaware.gov, updated weekly. A lender that is not listed and is not a bank should tell you under what authority it lends.
- Keep the papers: the Truth in Lending disclosure, the agreement and any messages about fees. Our guide on how to verify a lender lists what else to check.
- Call the office at (302) 739-4235 or (302) 577-6722, 8:00 a.m. to 4:30 p.m., Monday through Friday. Many questions can be handled by phone.
- Put the complaint in writing if it needs an investigation: email [email protected], fax (302) 739-2356, or mail 1110 Forrest Avenue, Dover, DE 19904, Attention: Compliance. The consumer complaints page has the printable form.
- Send a complaint to the CFPB as well if the lender is a bank or a bank partner.
Sources
- Delaware Code Title 5, Chapter 22, Subchapter I — Licensing (Delaware General Assembly)
- Delaware Code Title 5, Chapter 22, Subchapter III — Closed End Credit (Delaware General Assembly)
- Office of the State Bank Commissioner — consumer complaints
- State APR caps for $500, $2,000 and $10,000 installment loans, December 2025 (National Consumer Law Center)
We checked the facts on this page against these sources on October 27, 2026. Delaware's limits on fees and prepayment are in the statute; the price of the loan itself is set by your agreement.
Questions people ask
Is there a maximum interest rate on personal loans in Delaware?
Not for a licensed lender. Section 2229 of Title 5 lets a licensee charge the rate set by the loan agreement, and Section 2237 says other state limits on interest do not apply to these loans.
What fees can a Delaware lender charge if I pay late?
One delinquency charge per missed installment, of no more than 5% of that installment, under Section 2231.
Can a Delaware lender charge me for paying off my loan early?
No, not on a personal loan. Section 2234 lets you prepay in full at any time and bars prepayment fees for individual borrowers, except on residential mortgage loans.
Who regulates lenders in Delaware?
The Office of the State Bank Commissioner licenses lenders and handles complaints about small loan companies. Banks and bank partners may answer to federal regulators instead. See how to verify a lender.
Ask lenders for real offers
Describe the loan you have in mind. LendCedar passes your request to lenders and loan brokers who may contact you with offers; you compare them and decide.
- The loan you have in mind: amount, purpose, credit and income.
- Your contact details and your consent to be contacted.
- A lender or loan broker may contact you with an offer. Nothing is decided until you sign with a lender.
LendCedar is not a lender or a loan broker and does not make credit decisions.
You pay LendCedar nothing. Lenders and loan brokers pay us for requests, and they set their own rates and terms. How we make money.
Nearby in the guide
-
Offer term
Truth in Lending disclosures
The federal box line by line: APR, finance charge, amount financed, total of payments and what sits below.
-
Step
Verify a lender
Find the license on NMLS or with your state, match the lender of record and spot advance-fee scams.
-
Offer term
Late fees and returned payments
Where the late charge appears, why the APR leaves it out, state limits in Ohio and Florida, and federal rules.